Firms that can deposit into their general bank account funds in advance of having a client receivable so these can be used by the firm without constraints, can implementation Trust Functionality, without opening a Physical Trust Bank Account.
The trust functionality can be associated to a non-trust physical bank account for users to segregate funds applicable to a matter to then leverage the automated trust transfer process to improve the docket to collected business cycle.
In this case, the use of a trust GL bank account and a regular GL bank account both linked to the one physical general bank account, allows for all receipts, and subsequent withdrawals (payments) matter-specific or not, to go through it. The added operational benefit is the ability to segregate receipts received on a matter in advance of the invoice, so they can be applied against the invoice once generated at a future date.
Set-up of GL Accounts
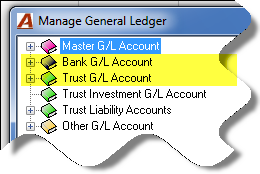
For every affected physical bank account, the user will need to create;
-
A GL account properties form within the Bank G/L Account section of the General Ledger. This GL bank account is for the portion of the account that will be managed as a general firm account and not a matter-specific trust-like GL bank account.
-
A GL account properties form (or as many as needed) within the trust G/L Account section of the General Ledger. This trust GL bank account is for the portion of the account that will be managed as a trust account. It will have the GL operations for matter specific receipts and withdrawals. On creation of the trust bank GL account, the trust liability GL account is automatically created.
As part of the creation process ensure that these GL bank accounts (general and trust) are:
-
Associated to the same Bank Institution and bank information.
-
Set to write cheques and debit memos.
-
Have different Cheque Sequence Number ranges, as this will make the bank reconciliation process easier.
Bank Reconciliation
The bank reconciliation process must be completed on the one physical bank account and with different cheque sequence numbers for each GL account affected, the user maintains visibility of source of outstanding cheques.